At $3.3M, Your Eichler's Tax Base Is Worth More Than You Think
Proposition 19 rewrote California's property tax transfer rules for both seniors who move and families who inherit. The details matter more when the homes in question are trading near $3.3 million.
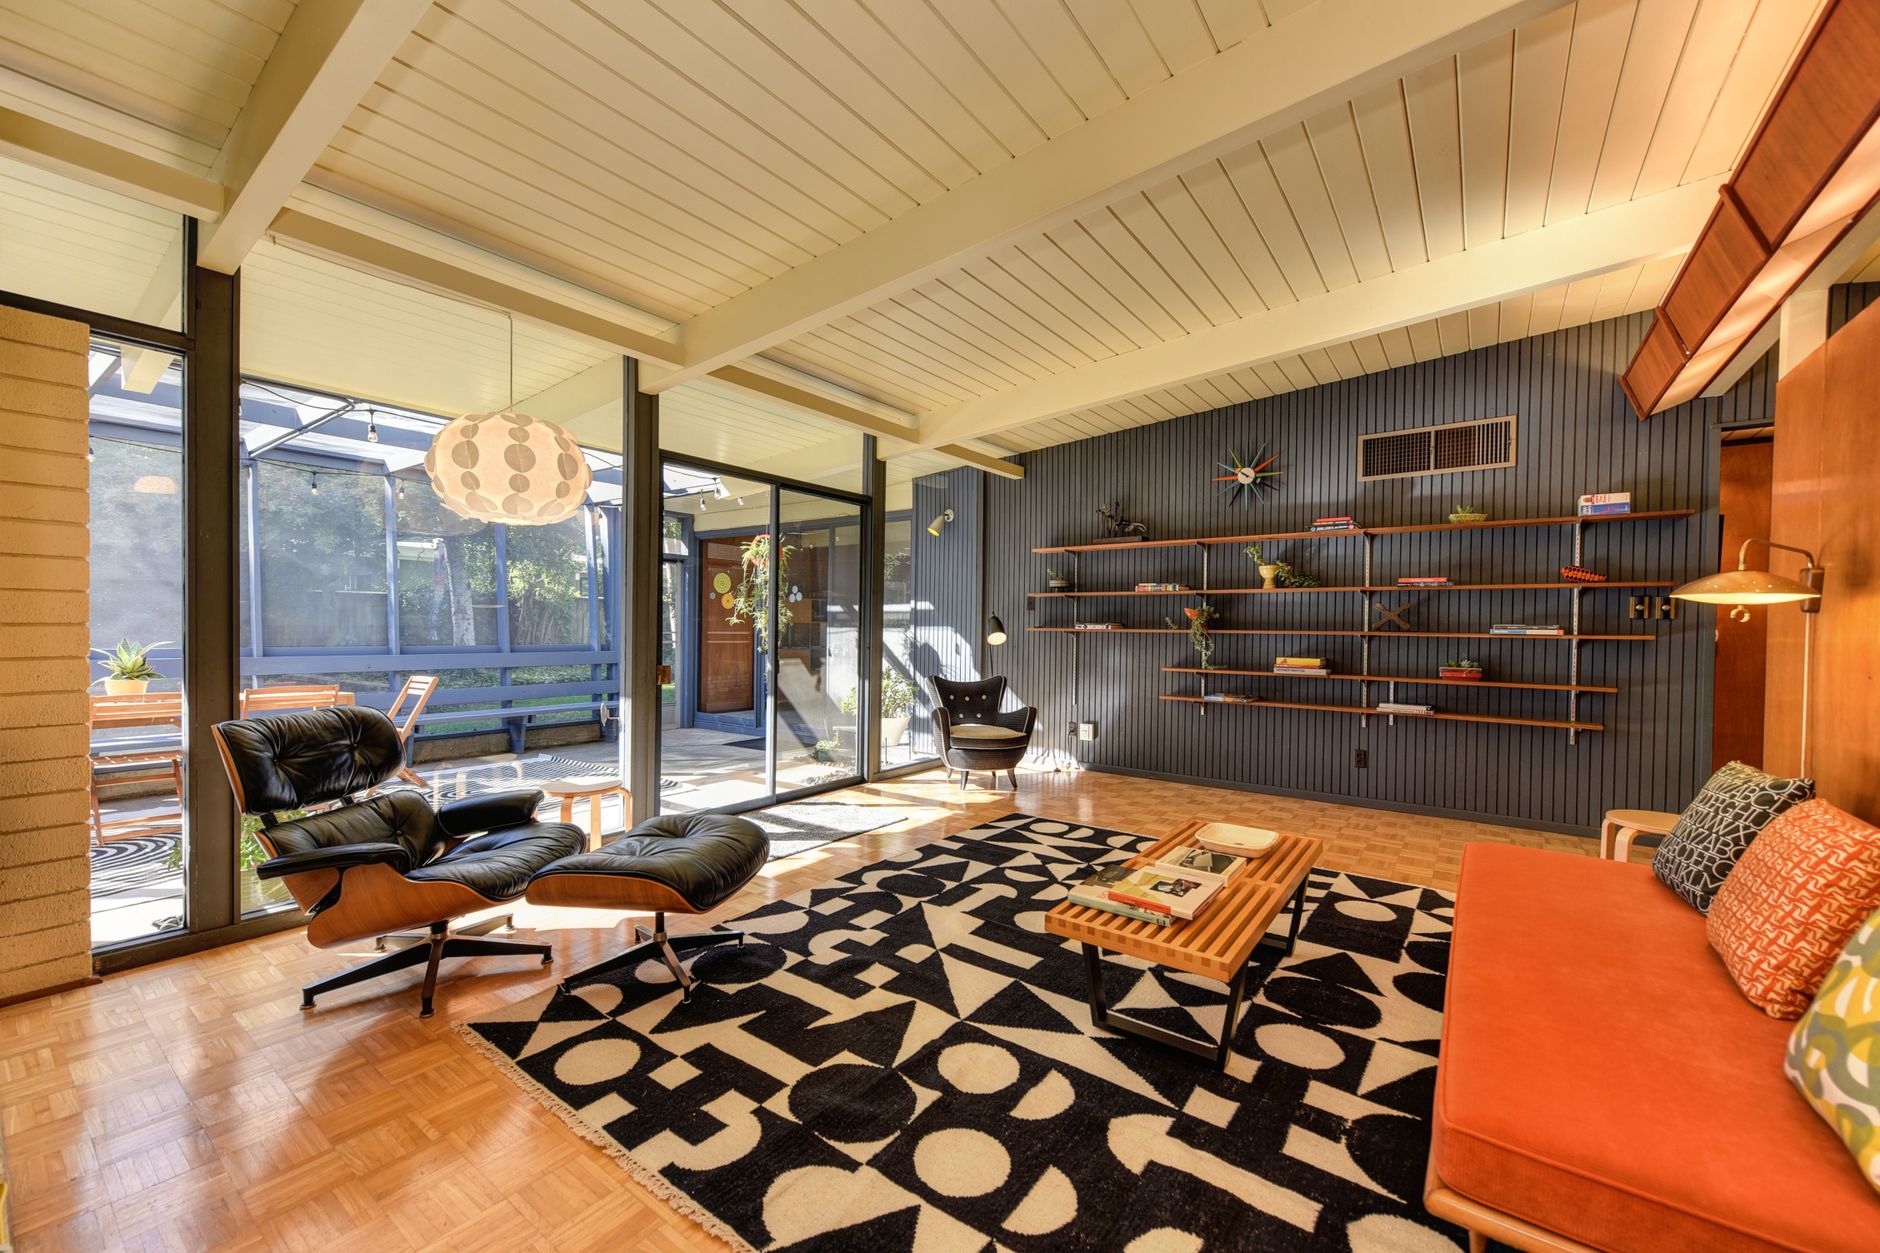
Why This Matters in Eichler Tracts
Among the 20 recorded sales in our dataset, the trailing-12-month median for single-family Eichler-area homes sat at $3,340,000 across 18 sales. At that price level, a property tax base locked in from a purchase made decades ago is worth protecting — and California's Proposition 19 governs exactly how that base can move with you or pass to your children.
Prop 19 has two mostly separate parts: a base-year transfer for owners who are 55 or older (or disabled), and an intergenerational exclusion for parent-to-child transfers. They run on different rules and different timelines.
Part One: Moving and Taking Your Tax Base with You
Proposition 19 allows persons over 55 years of age to transfer the taxable value of their principal residence to a replacement principal residence located in any California county, up to three times, provided certain requirements are met. That statewide portability — replacing the old county-by-county patchwork — is the headline change.
Who qualifies. A claimant must be at least age 55 when their original property sells. In order to transfer the base year value, you must be at least age 55 when you sell your original primary residence. Your age when you purchase your replacement primary residence is not relevant. If spouses are co-owners and only one is 55, as long as the spouse who is at least age 55 is an owner of both the original property on its date of sale and the replacement dwelling on its date of purchase, the exclusion may qualify. The spouse who is under the age of 55 does not preclude the other from qualifying.
The timing rule. As long as one transaction occurs on or after April 1, 2021, and the original home is sold within two years of the purchase of the replacement home, the base year value of the original home can be transferred to the replacement home. You can buy first or sell first, but the window between transactions is two years.
What transfers. "Taxable value" means the property's base year value plus inflationary adjustments, commonly referred to as the factored base year value. That number — not the old tax rate itself — moves to the replacement home.
The value comparison test. The replacement can cost more than the original. If the replacement home is of equal or lesser value than the original home, the original home's factored base year value may be transferred without any value adjustment. "Equal or lesser value" means 100% or less of the full cash value of the original home if a replacement home is purchased before the sale of the original home, 105% or less if purchased within the first year after the sale, or 110% or less if purchased within the second year after the sale. If the full cash value of the replacement home is greater than the adjusted full cash value of the original home, the base year value may still be transferred, but with any excess value added on. The new taxable value of the replacement home is the sum of the adjusted base year value of the original home plus the difference between the two full cash values. In short, you do not lose the transfer just because you buy up — you simply pay tax on the gap.
Three-transfer limit. Under Proposition 19, three transfers will be allowed for homeowners who are over age 55 or physically and permanently disabled, regardless of whether a property owner previously transferred a base year value under Propositions 60/90 and Proposition 110.
How to apply. Proposition 19 base year value transfer claim forms are available from and filed with the Assessor of the county where the replacement home is located. For an age-based transfer, the form is BOE-19-B. To qualify, the claim must be filed with the County Assessor within three years of the date you purchased or completed construction on the replacement home. The base year value transfer is still available for claims filed after the three-year period; however, the transfer will be granted beginning with the year that the claim is filed — meaning you lose the retroactive tax savings but not the right to transfer. File with the Santa Clara County Assessor's office when buying in-county, or with the assessor in whichever California county the replacement sits.
Part Two: Inheriting the Family Home
Prop 19 narrowed the old Proposition 58 exclusion considerably. The core rule now: Proposition 19 limits the parent-child transfer exclusion to a transfer of a family home that is the principal residence of the transferor and becomes the principal residence of the transferee, or a family farm. The transfer of a rental home between parents and children would not qualify for the exclusion. An Eichler used as investment property does not qualify; an Eichler that was the parent's primary home can.
The residency requirement. The transferee must live in the home as their primary residence within one year of transfer to qualify for the exclusion. The transferee must file for the homeowners' exemption or disabled veterans' exemption on the residence within one year of the transfer to receive the intergenerational exclusion as of the date of the transfer. Miss the one-year window and the exclusion, if granted at all, applies only going forward.
The ongoing obligation. At least one eligible transferee must continually live in the property as their family home for the property to maintain the exclusion. Once the property is no longer your principal residence, it will receive a new taxable value as of the lien date following the date you no longer occupy it.
When siblings are involved. If multiple siblings inherit the family home, only one of the siblings needs to live in it. If that sibling moves out and another sibling moves in within one year of the move-out date, the exclusion will continue. The exclusion is not available for transfers of property between siblings.
The value cap. The excludable amount is capped at an amount equal to the principal residence's factored base year value at the time of the transfer plus $1,044,586. That figure is adjusted every two years by the BOE based on California's house price index; the current amount applies to intergenerational transfers occurring from February 16, 2025, through February 15, 2027, and the BOE is required to calculate and publish the adjustment every other year based on the Federal Housing Finance Agency's House Price Index for California. If the market value exceeds this limit, the amount exceeding the value limit will be added to the factored base year value. Given the median sale price in this market, many inherited homes will exceed the cap and carry a partially reassessed tax value.
Date of transfer on inherited property. If the property was inherited as a result of a death, the date of death is considered the date of transfer for property tax purposes, not the date the property was distributed. File accordingly — the clock on the one-year exemption deadline and the three-year claim deadline both run from the date of death.
How to apply. The form for parent-to-child transfers on or after February 16, 2021 is BOE-19-P, filed with the county assessor where the property sits. The exclusion claim must be filed within three years from the date of death or transfer, or before transfer to a third party, whichever is earlier.
The Tax Consequences of Getting It Wrong
Both provisions require active filing. Neither happens automatically. An heir who moves into a parent's Eichler but forgets to file the homeowners' exemption within 12 months, or a seller who waits more than three years after buying their replacement home to file a claim, can lose the most favorable treatment. The assessor's office does not issue reminders.
Property tax strategy involving trusts, estates, or partial interests is fact-specific. Consult a tax adviser or attorney — the county assessor's office can tell you whether a claim was granted, not whether your particular ownership structure qualifies.
Where to Check
- California BOE — Proposition 19 Overview: Forms, filing checklists, and FAQ for both base-year transfers and intergenerational exclusions.
- BOE Publication 800-3: Base Year Value Transfers — Age 55 and Older: Plain-language walkthrough of the value comparison test and how to apply.
- BOE Publication 800-1: Transfers Between Parents and Children: Step-by-step guide to the intergenerational exclusion, with examples.
- BOE Prop 19 Fact Sheet: Side-by-side summary of both provisions with value-limit examples.
- BOE Letter to Assessors 2024/044 — Base Year Value Transfer Q&A: The most recent detailed guidance on timing and value calculations.
- BOE News Release — 2025 Intergenerational Exclusion Amount: Current $1,044,586 cap, effective through February 15, 2027.
- BOE Property Tax Rule 462.540: The formal regulation governing base-year value transfers.
Tim McMullen · CA DRE #02016832
[email protected] · (415) 691-9272
- https://www.boe.ca.gov/prop19/
- https://www.boe.ca.gov/pdf/pub800-3.pdf
- https://www.boe.ca.gov/pdf/pub800-1.pdf
- https://www.boe.ca.gov/pdf/pub801.pdf
- https://boe.ca.gov/proptaxes/pdf/lta24044.pdf
- https://boe.ca.gov/proptaxes/pdf/lta22009.pdf
- https://www.boe.ca.gov/proptaxes/pdf/lta21019.pdf
- https://www.boe.ca.gov/news/2025/NR-25-02.htm
- https://www.boe.ca.gov/proptaxes/pdf/rules/Rule462-540.pdf
- https://boe.ca.gov/proptaxes/pdf/sample-boe19b.pdf
Tim McMullen, CA DRE #02016832. Real estate services provided by Tim McMullen, Broker, CA DRE #02016832. Figures are from recorded sales; nothing here is an opinion of the value of any home.